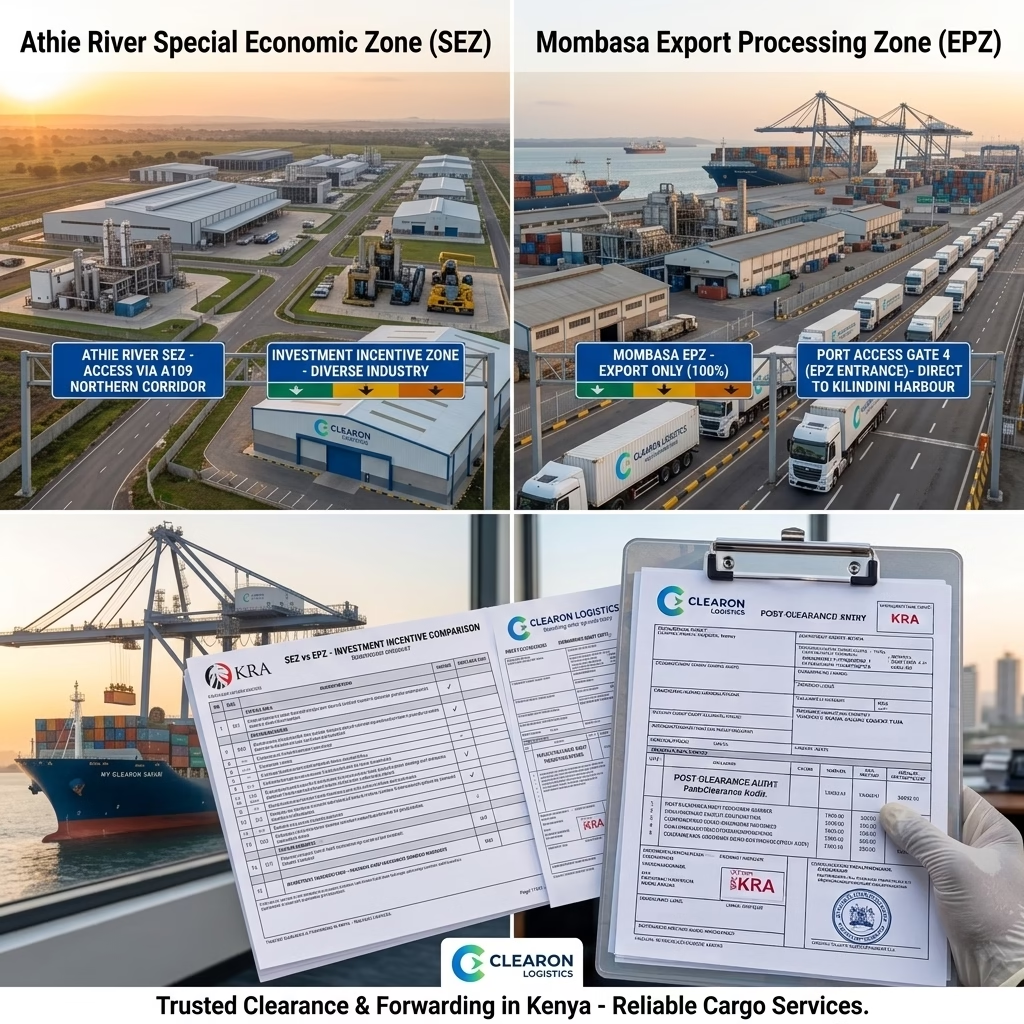
Special Economic Zones vs Export Processing Zones in Kenya is a decision that shapes not just your tax rate, but what your business is even allowed to do under the incentive framework you choose. Both offer genuinely significant benefits for businesses setting up in Kenya — but they were built for different purposes, and picking the wrong one can mean either overpaying for flexibility you don’t need, or getting locked into export requirements that don’t fit your actual market.
Table of Contents
The Older Model: Export Processing Zones
Kenya’s Export Processing Zones (EPZ) programme has operated since 1990 under the Export Processing Zones Act, Cap 517, administered by the Export Processing Zones Authority (EPZA). It’s Kenya’s longest-running special incentive regime, and by scale, one of its most successful — by 2024, Kenya had 105 gazetted EPZs with 180 operating enterprises, capital investment of KSh 171.9 billion, and total EPZ sales of KSh 136.2 billion, with Mombasa County hosting the highest concentration at 28 zones.
EPZs are built specifically for export-oriented manufacturing. Enterprises are generally required to export at least 80% of their output, and the programme has been particularly significant for Kenya’s garment and textile sector exporting under AGOA to the United States.
The Newer, Broader Model: Special Economic Zones
Special Economic Zones (SEZ), established under the Special Economic Zones Act 2015 and regulated by the Special Economic Zones Authority (SEZA), were introduced specifically because EPZs, despite their success, were seen as too narrow — limited to export-oriented manufacturing and excluding services, domestic-market production, and the broader range of activities SEZs now accommodate.
SEZs support manufacturing, services, logistics, tourism, and professional services — a materially wider scope than the EPZ model, designed to draw on lessons from more comprehensive multi-purpose zone regimes elsewhere, particularly in Asia.
Tax Treatment Side by Side
| Incentive | EPZ | SEZ |
|---|---|---|
| Corporate tax | 10-year holiday, then 25% | 10% for first 10 years, 15% for next 10 years |
| Standard comparison rate | Kenya’s standard corporate rate is 30% | Same 30% standard rate |
| VAT | Exemption on raw materials, machinery, and equipment | Duty and tax exemptions on qualifying goods |
| Withholding tax | Exemption on dividends to non-resident shareholders | Included among broader fiscal incentives |
| Scope of eligible activity | Export-oriented manufacturing only | Manufacturing, services, logistics, tourism, professional services |
Both regimes offer a meaningfully lower tax burden than Kenya’s standard rates — the question is less “which saves more tax” and more “which scope of business activity actually fits what you’re building.”
The Key Structural Difference
The 80% export requirement is the defining constraint of the EPZ model — it works well for a business genuinely built around exporting, but it’s a poor fit for a company that wants meaningful flexibility to sell into the Kenyan or regional market. SEZs don’t carry the same rigid export threshold, making them the more natural fit for businesses with a mixed local-and-export strategy, or those in services and logistics rather than pure manufacturing.
This is closely related to, but distinct from, the export-orientation trade-off in Manufacture Under Bond, which carries its own 20% domestic sales allowance — worth comparing directly against both EPZ and SEZ if you’re evaluating incentive frameworks for a manufacturing operation specifically.
Selling Into the Kenyan Market
SEZ entities face no restriction on selling locally — but goods sold into the Kenyan market are liable for the same taxes and levies as any standard import, meaning the tax benefit applies to the SEZ-based operation itself, not to goods once they leave the zone and enter domestic circulation. This “no restriction, but standard taxation on domestic sales” structure gives SEZ businesses genuine flexibility to serve both export and local markets, just without double-dipping on tax-free treatment for both.
Which One Fits Your Business
- Choose EPZ if: your business is genuinely, overwhelmingly export-oriented manufacturing, and the 80% export requirement isn’t a meaningful constraint on how you actually plan to sell
- Choose SEZ if: you want broader flexibility — services, logistics, tourism, or a manufacturing operation that expects to sell meaningfully into the Kenyan or regional market alongside exports
- Consider Manufacture Under Bond as an alternative if you’re specifically focused on manufacturing with some domestic sales flexibility, but don’t need the broader physical zone infrastructure that EPZ and SEZ designations provide
Making the Right Call Before You Commit
Choosing between these frameworks isn’t just a tax decision — it shapes your physical location options, your permitted business activities, and how much flexibility you have to adjust your sales strategy over time. Getting locked into the wrong regime because it looked like the better tax deal on paper, without weighing the activity restrictions, is a costly mistake to unwind later.
At Clearon Logistics, while incentive-scheme selection itself sits with your investment advisors, we help businesses understand how their choice of EPZ, SEZ, or another framework affects the practical import and clearance side of their operation — what documentation changes, how machinery and input imports are treated, and what to expect once goods are moving in and out of a zone-based operation.
Setting up manufacturing, services, or logistics operations in Kenya and weighing your incentive options? Talk to Clearon Logistics about how each framework affects your import and clearance process.
Frequently Asked Questions
Which offers lower corporate tax, EPZ or SEZ? Both offer significantly reduced rates compared to Kenya’s standard 30% corporate tax — EPZ gives a full holiday for 10 years then 25% after, while SEZ offers 10% for the first 10 years and 15% for the following 10 years. Which is genuinely lower depends on your specific timeline and profitability profile.
Can an EPZ business sell into the Kenyan domestic market? EPZ enterprises are generally required to export at least 80% of output, making them a poor fit for businesses wanting significant domestic sales flexibility — SEZ is generally the better fit for that need.
Do SEZ businesses pay tax on goods sold locally? Yes — SEZ entities face no restriction on selling locally, but goods sold into the Kenyan market are subject to standard taxes and levies, the same as any other domestic sale.
Is Manufacture Under Bond the same as EPZ or SEZ? No — MUB is a separate scheme with its own structure, generally offering more flexibility around domestic sales (up to 20%) than the EPZ export requirement, but without the same physical zone infrastructure that EPZ and SEZ designations provide.
Further Reading
- Special Economic Zones Authority (SEZA) Kenya (external, dofollow)
- Export Processing Zones Authority (EPZA) Kenya (external, dofollow)
- Related on our blog: Importing Machinery into Kenya: Manufacture Under Bond and Investment Incentives
- Related on our blog: Bonded Warehouse Kenya: How to Defer Duty and Protect Cash Flow
- Our service: Clearing and Forwarding Services in Kenya
Leave a Reply